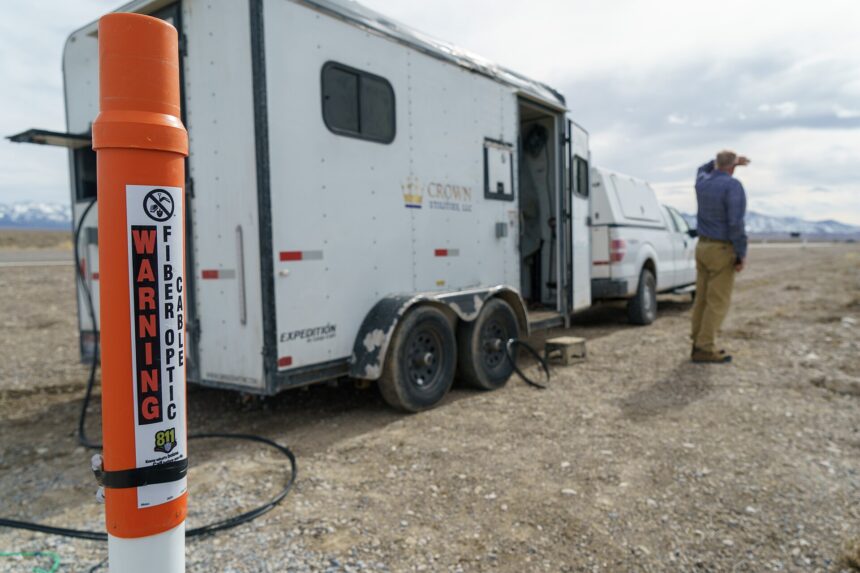
For most of the past decade, the debate over closing America’s broadband gap was framed as a contest: fiber against wireless, wired networks against everything else. The numbers coming out of 2026 suggest that framing is out of date. Fiber construction funded by the federal BEAD program is finally reaching the ground, and fixed wireless has quietly become one of the largest home internet options in the country. The two are filling different parts of the same map.
Fixed wireless is now mainstream
Fixed wireless access, which delivers home internet over cellular networks to a receiver in the house, passed 17 million U.S. connections across Verizon, T-Mobile and AT&T in the first quarter of 2026, according to an Ookla analysis. That is 13.74 percent of the nation’s 123.75 million home broadband subscriptions, based on Census Bureau survey data.
The more surprising finding is where it is being used. Fixed wireless was pitched as a rural fix, but about 70 percent of Ookla’s second-quarter fixed wireless speed tests came from urban users, IEEE ComSoc’s summary of the report noted, though Ookla cautions that test volume is not a direct measure of subscribers. ComSoc’s summary described fixed wireless as having matured into “a credible alternative to traditional fixed broadband.”
Fiber is moving from paperwork to construction
On the wired side, the $42.45 billion BEAD program spent years in planning, challenges and a 2025 federal restructuring. This fall it is producing shovels in the ground. In Louisiana, state officials and REV Fiber marked the start of a project bringing fiber to 2,840 locations in East Baton Rouge Parish, Broadband Breakfast reported, with construction expected to begin in November and take about seven to eight months. Louisiana’s broadband office says construction for nearly 15,000 locations across 23 parishes is projected to be finished by the end of the first quarter of 2027, with nearly 1,800 miles of fiber being deployed, according to a state release.
Pennsylvania announced more than $448 million in BEAD grants on October 2 for projects in 50 counties, with more awards expected by the end of the year, according to the Pennsylvania Broadband Development Authority. Michigan said it signed 23 BEAD agreements on October 19 to move projects closer to construction.
Fixed wireless is part of the BEAD picture too. Federal broadband officials highlighted a BEAD-funded fixed wireless tower serving Ogallala, Nebraska, earlier this year:
.@ariellerothNTIA & @TeamPillen also visited the tower @vistabeam is using to provide broadband service to Ogallala through BEAD.
Thanks to advances in fixed wireless, consumers are benefiting from faster speeds over longer distances, lower costs, and quicker deployment! pic.twitter.com/GigfXvAbv6
— NTIA (@NTIAgov) May 15, 2026
Why the two technologies complement each other
The practical lesson of 2026 is that each technology does what the other cannot. Fiber is a long-lived asset with enormous capacity, and once it is in the ground it can be upgraded for decades by changing the electronics at either end. But it takes crews, permits and months of construction to reach each new street. Fixed wireless can be switched on wherever a cell site has spare capacity, often in days, which makes it a fast way to give households a real choice while fiber is still being planned.
The two also feed each other. Every fixed wireless connection depends on a cell site, and every modern cell site depends on fiber running back into the network. A dense fiber buildout makes wireless networks stronger, and growing wireless demand gives builders more reasons to extend fiber. Treating them as rivals misses how much of the same infrastructure they share.
The challenges are real
None of this means the job is close to done. Most BEAD-funded construction will not deliver service to end users until 2027 or 2028, according to a BEAD funding tracker, and Pennsylvania’s own timeline shows construction starting in 2027 and service by 2030. Families in unserved areas will be waiting a while longer.
Fixed wireless has limits as well. Capacity on a cell site is shared, and Ookla found that foliage and daily peak-hour congestion affect performance, with fewer than 40 percent of fixed wireless speed tests meeting the federal 100/20 Mbps broadband benchmark in 48 states. That is the trade-off of a technology built for speed of deployment rather than raw capacity, and it is why fixed wireless works best as part of a broader network rather than as the whole answer.
Then there is labor. A study by the Fiber Broadband Association and the Power & Communication Contractors Association estimated that current federal and state programs would require about 58,000 additional construction workers and technicians, according to the Fiber Broadband Association. That is a constraint, but it is also an opportunity: these are skilled, well-defined jobs in many of the same rural communities the networks are built to serve.
What to watch
Over the next year, the signals worth tracking are concrete ones: how many BEAD projects move from signed agreements to active construction, whether states hit timelines like Louisiana’s early-2027 target, how fast fixed wireless subscriptions keep growing, and whether training programs keep pace with the demand for crews. If those numbers keep moving in the right direction, 2026 will be remembered as the year America’s broadband buildout stopped being a plan and became a construction project.
Roger Sartain is SVP and General Manager of Wireless & OSP at Telamon.
Related reading: The FCC Says 99.7% of Americans Can Get Satellite Broadband.